Sep 30, 2026 · @Jennifer Kirk
Mortgage rates crossed 7% this month. That's the headline for North Dallas buyers and sellers this fall, and it matters more than any price chart.
"Should we wait?" is the question I'm hearing most right now. Fair question. It deserves real numbers, not a pep talk.
Here's the part I want you to understand: prices in DFW are basically flat. The PAYMENT is what moved.
What happened in September
Rates jumped fast. The 30-year fixed averaged 6.66% at the end of August and 7.03% by September 24. The Federal Reserve raised its policy rate by 25 basis points on September 16, and mortgage rates had already started climbing ahead of it.
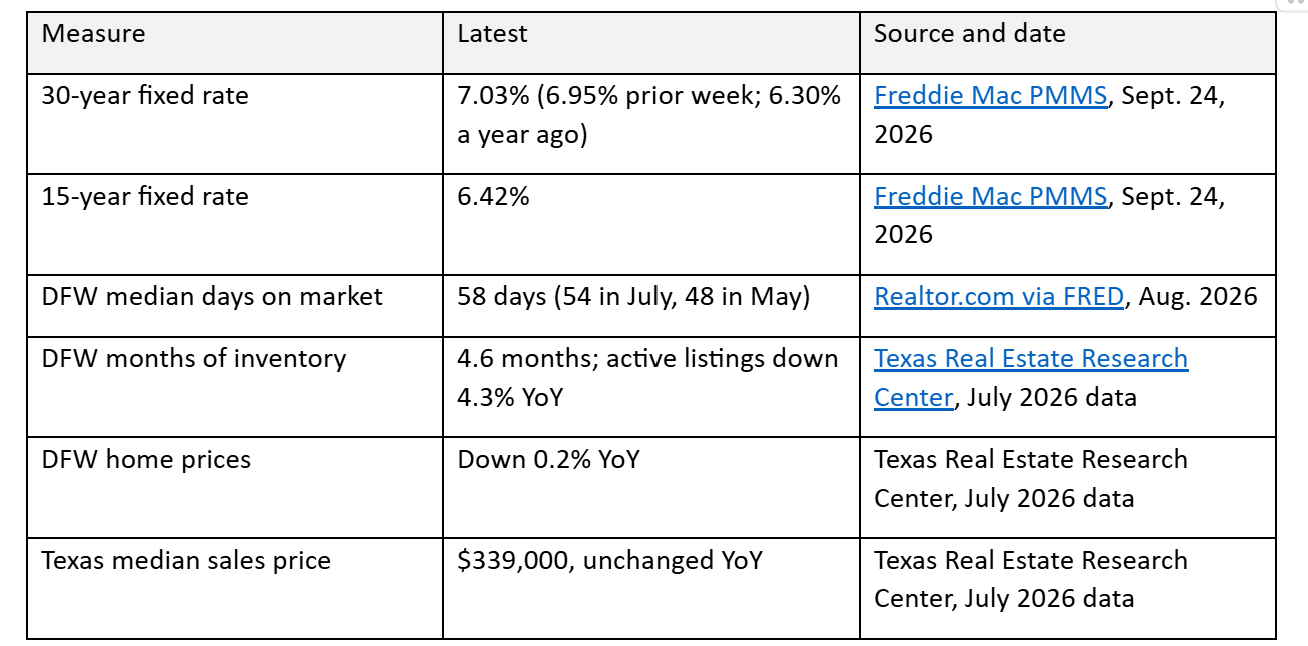
Read that table top to bottom and the story is clear. Prices? Flat. Inventory? Tighter than a year ago. Time on market? Longer every month since spring. Rates? UP.
Freddie Mac's survey reflects conventional loans with 20% down and excellent credit. Your rate may differ.
What it means for buyers
Here's the math. On a $400,000 loan, principal and interest at 6.66% runs approximately $2,571 a month. At 7.03%, it's approximately $2,669.
That's roughly $99 more per month. About $1,185 more per year. Same house. Same price.
And that is NOT your full payment. Property taxes, insurance, HOA, and any MUD (municipal utility district) or PID (public improvement district) assessments sit on top of it. In Little Elm, Aubrey, or Celina, those pieces can move your payment more than a rate change does. Two homes at the same price, six miles apart, can cost very different amounts every month.
The good news is that you have more room to negotiate on resale. Homes are sitting longer, and many sellers are open to concessions. A seller-paid rate buydown may lower your payment more than the same dollars off the price, depending on the loan and your eligibility.
🚨 On new construction, builder incentives get louder when rates rise. They're usually tied to the builder's preferred lender. Compare the TOTAL loan cost against an outside lender before you sign anything and bring your own agent before you walk into the model home. The builder's rep works for the builder.
Calculations are approximate, principal and interest only, 30-year fixed, and for illustration. Actual rates and payments are subject to lender approval and qualification.
What it means for sellers
Here's the part sellers sometimes get wrong: your buyer isn't shopping price. They're shopping payment.
When rates rise, every buyer's budget shrinks. At 7.03%, the same monthly principal and interest that covered a $400,000 loan at 6.66% now covers roughly $385,000. Your buyer didn't change. Their buying power did.
And in Prosper, Frisco, or Celina, you're not just competing with the house down the street. You're competing with a builder two miles away who can buy down a buyer's rate and make a higher price produce a lower payment.
So compete on payment, not just price:
- Price for today's buyer, based on current comps, not a 2022 number.
- Consider a rate-buydown concession. It may move a buyer more than a price cut and could cost you less in net proceeds.
- Skip the big renovation. Fix the small things, service the HVAC, and clean everything.
And if you're holding a 3% rate with no real reason to move? Waiting may be the right call for you. I'll show you that math too.
My take
I'm not going to tell you where rates go next. Nobody knows, and anyone who promises you they'll drop is guessing.
What I can tell you is how to decide with the numbers in front of you. Buying isn't automatically the right move for everyone, and waiting has a cost too. The only way to know which applies to you is to run YOUR payment.
Because you don't live in the rate headline. You live in the PAYMENT.
📲 Want me to run the numbers on a specific home or neighborhood? DM me "RATE" on Instagram @JenniferKirkRealtor, or call 214-592-7605.
Jennifer Kirk, REALTOR® · Real Broker, LLC · Equal Housing Opportunity. I'm not a lender, tax advisor, or financial advisor; talk with a licensed lender about your specific situation.
Sources
- Freddie Mac Primary Mortgage Market Survey, survey dated Sept. 24, 2026. Historical averages shown; individual mortgage rates vary.
- Texas Real Estate Research Center, Texas Housing Insight, September 2026 (July 2026 data)
- Realtor.com, Median Days on Market, Dallas-Fort Worth-Arlington (FRED MEDDAYONMAR19100), August 2026
FROM OUR BLOG
What Credit Score Do You Need to Buy a House in North Dallas?
"My credit isn't good enough to buy a house." The floor may be lower than you think. FHA (Federal Housing Administration) loans allow a minimum score of 580 for maximum financing, or 500–579 with at least 10% down (HUD Mortgagee Letter 2026-11, October 8, 2026). VA (U.S. Department of Veterans Affai
How Long Does It Take to Sell a House in North Dallas Right Now?
"We'll list it now and be moved by Thanksgiving, right?" Short answer: plan on roughly three to four months from the day you list to the day you close. In September 2026, the median listing spent about 65 days on the market in Collin County and 63 days in Denton County (Realtor.com data via FRED, th
Why Are Property Taxes So High in Texas? What You'll Actually Pay in North Dallas
"Everyone keeps warning us about Texas property taxes. How bad is it, really?" Short answer: Texas has no state income tax and no state property tax, so cities, counties and school districts fund themselves largely through local property tax. In Frisco, the combined 2026 rate is approx. 1.68% of tax